Your Local Mortgage Lender
Located in Incline Village, Nevada
Personalized Mortgage Experience
Shay Phillips offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Incline Village, Nevada.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
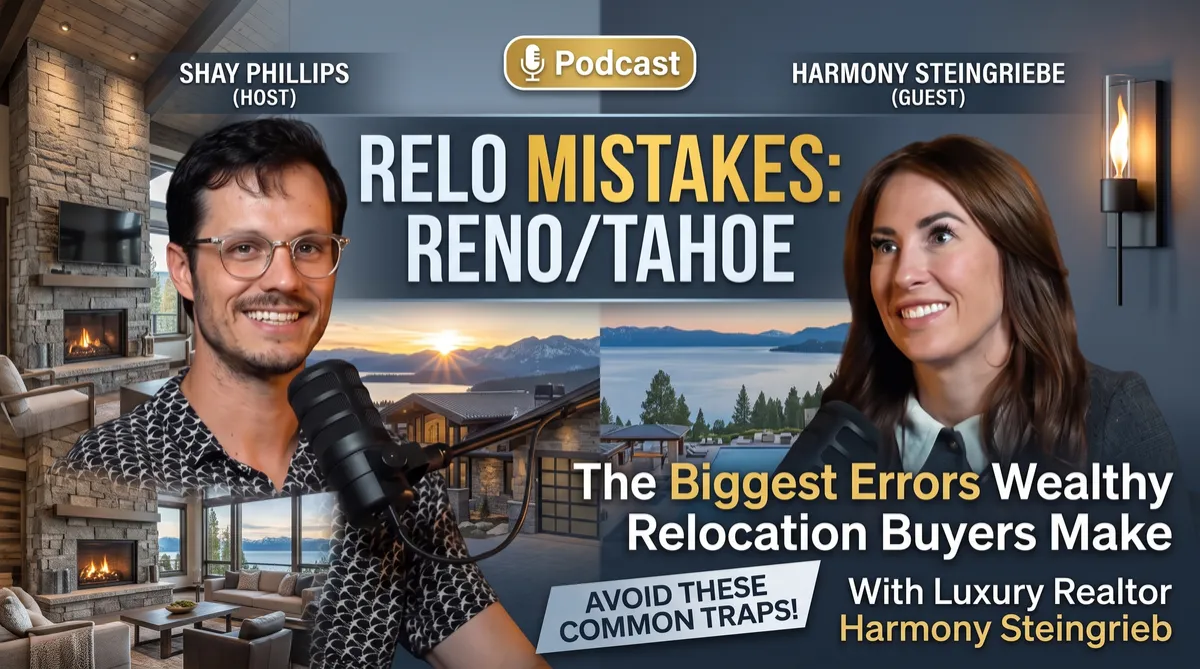
The Biggest Mistakes Wealthy Relocation Buyers Make in Reno Tahoe and How to Avoid Every One
The Conversation Wealthy Relocation Buyers Need to Have Before They Fall in Love With a Listing
Shay Phillips sat down with Harmony Steingriebe, a luxury realtor serving the Reno and Tahoe region who is licensed in both California and Nevada, for a conversation built specifically for wealthy buyers considering a relocation to one of the most compelling lifestyle markets in the country. Harmony has been in real estate for nearly ten years, has been part of the number one Tahoe team and the number one all-female real estate team in the nation, has sold close to one hundred and fifty million dollars in volume, and went independent two years ago through Sierra Sotheby's.
The conversation covers terrain that Zillow, Google, and ChatGPT cannot cover. And that gap between what is searchable and what actually matters is exactly where the right advisor earns their value.
Mistake One: Falling in Love With the House Before Understanding the Lifestyle Around It
This is the most common and most costly mistake Harmony sees from affluent relocation buyers. They find a home on Zillow. The price makes sense. The photos look incredible. They are emotionally attached before they have ever spoken to anyone who knows what daily life in that neighborhood actually feels like.
Two concrete examples from the Incline Village market illustrate how significant this gap can be.
Upper Tyner versus the Eastern Slope. On a listing platform both neighborhoods might show homes at dramatically different price points. Upper Tyner is less expensive and a buyer who sees only the numbers assumes they have found an obvious win. What they have not seen is the elevation difference, the snow load that comes with it, the driveways that run north-facing, and the commute into town that changes meaningfully when a heavy storm hits. Someone who moved to Incline Village to ski every weekend and be first chair does not want to discover they have ten feet of snow and ice blocking the garage every storm.
The golf course community question is another version of the same mistake. Many of Harmony's clients arrive having decided they want a golf course community and having identified a specific property in Montreux. Montreux is beautiful. The trees and the setting are genuinely spectacular. But Montreux has a six-month golf season due to elevation. An hour away as the crow flies, Arrow Creek offers year-round golf across two eighteen-hole courses with access to both through a single membership. For a buyer whose lifestyle centers on golf the difference between those two communities is not a minor detail. It is the core of the decision.
Roof Pitch, Driveway Orientation, and the Details That Actually Determine Daily Life
In high snow load areas the mechanics of a property matter in ways that are invisible to someone touring in July. The pitch of the roof determines where snow sheds. A roof that deposits snow directly into the driveway combined with a north-facing driveway that stays shaded through most of the day is a property where ice management becomes a full-time winter obligation.
Harmony walks through these specifics on every showing in snow country. Where does the roof drain? Which direction does the driveway face? How much sun does it get? These are not cosmetic questions. They determine whether the lifestyle the buyer imagined is actually the lifestyle they will live.
How to Think Through Lifestyle Design Before You Choose a Property
Harmony's tactical advice for buyers considering relocation is to identify the top three things they do in their day-to-day life that they may be taking completely for granted. Not the bedrooms and bathrooms and garage bays. The small things. The morning dog walk in a flat neighborhood. The Sunday routine of walking to a specific coffee shop. The evening ritual that happens because the geography of where they live enables it.
Those daily habits are what make a place feel like home versus a place that looks great in listing photos. They are also the first things that disappear when someone relocates without thinking through whether the new location supports them. Four bedrooms, an office, and a three-car garage describe a house. The morning walk, the favorite Sunday coffee spot, and the evening ritual describe a life. Both matter but buyers typically spend all of their analytical energy on the former and almost none on the latter.
Nevada Tax Benefits Versus Florida and Texas
The tax conversation is one that draws a significant portion of Reno and Tahoe's relocation buyers and Harmony is careful to note she is not a CPA and recommends bringing in tax professionals for the specific strategic planning. But she is happy to explain the framework that most buyers have not fully considered before arriving.
Nevada has no state income tax. That is the well-known part. What is less known is that Nevada is an assessed value state rather than a market value state for property tax purposes. In California, which produces a significant portion of Reno and Tahoe's relocation buyers, property taxes are based on the purchase price of the home. In Nevada property taxes are based on an assessed value that is anchored to the market value of the home in the year it was built.
The practical implication is striking. A charming home in Reno's midtown or old southwest neighborhoods built in the nineteen-fifties might be worth seven hundred thousand to a million dollars on the current market but carry annual property taxes of less than fifteen hundred dollars. As Shay noted a four hundred and fifty thousand dollar cookie-cutter suburban home in Fort Worth carries fourteen thousand dollars in annual property taxes with no state income tax. Texas has no income tax but the property tax burden carries the full weight of what state income tax would otherwise fund. Nevada does neither.
Florida is a similar story. No state income tax is the headline but property taxes and increasingly proposed capital gains taxes and inheritance taxes in other non-income-tax states are changing the full picture for wealthy buyers doing a comprehensive analysis. Seattle-area buyers specifically are evaluating inheritance and retirement tax proposals that are making Nevada's complete tax environment look more favorable than it has in previous years.
Choosing the Right Advisor and Why It Changes Everything
The most important section of this conversation and the one Harmony returns to throughout is what actually separates a great real estate advisor from an adequate one, particularly in the luxury relocation market.
The information gap has largely closed. Wealthy buyers have Google. They have Zillow. They have AI. They can find listings themselves in minutes. What they cannot find through any of those channels is access.
Access to the right contractors who are already trusted by people at similar price points. Access to the right architects, designers, and restoration professionals. Access to doctors, CPAs, attorneys, and lenders who understand the specific situation of a high-net-worth buyer building a new life in a new place. Access to the community itself in a way that makes the transition feel welcoming rather than isolating.
Harmony describes her role at higher price points as feeling less like finding someone a home and more like helping someone build a life and feel part of something. The introductions that come with the right advisor are worth more than the transaction itself over any meaningful time horizon because they determine whether the buyer arrives in Reno Tahoe feeling supported and connected or feeling like a stranger who owns an expensive house.
The other component is confidence. High-net-worth buyers are extraordinarily capable in their own domains. What they are buying when they hire a trusted real estate advisor in a market they do not know is the confidence to make a million or five million or eight million dollar decision knowing that someone with deep local knowledge has fully evaluated the pros, the cons, the details, and the lifestyle implications on their behalf.
That confidence is not available from any listing platform. It comes from the relationship with the right person.
How to Reach Harmony Steingriebe
Visit LuxuryRenoTahoeProperties.com or find Harmony on Instagram at Harmony Steingrebe. Links are in the description.
Shay Phillips works with buyers on mortgage financing for Reno, Tahoe, and surrounding Nevada markets. Reach out to Shay Phillips to connect on the lending side of your relocation purchase and get pre-approved before the right property appears.
Sources
NevadaRealtors.org
NAR.realtor
MortgageNewsDaily.com
NevadaDepartmentofTaxation.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

